Tower Rush Demo
 FUN Demo
Pros
- Identity and address checks reached approval in both the 1win and CroreBet withdrawal cases.
- A complete replacement resolved the cropped address-document problem within the existing request.
- A later small withdrawal reused an existing KYC decision in the account test.
Cons
- Registration and a successful deposit did not remove the later document requirement.
- Melbet required a separate source-of-funds statement before approving the tested withdrawal.
- Changing payment details triggered a separate method check despite an existing KYC decision.
Tower Rush operator KYC and documents concern the account that holds your balance. Galaxsys supplies the game; the operator handles the account, verification request and external payment. For a reader in Bangladesh, the relevant conditions are those of the particular account and BDT transaction, including who owns the receiving wallet.
KYC means “know your customer”: checking the person behind an account and the information relevant to its use, a task that an email confirmation or a payment authorised with a wallet PIN does not automatically complete.
Tower Rush operator KYC and documents across six Bangladesh accounts
The first-withdrawal requests differed across my six Bangladesh accounts, even though each test used the original Tower Rush from Galaxsys and a personal payment account in BDT.
I received no new document request during registration or the first deposit in these six cases. At withdrawal, three operators requested additional material. The other three processed the particular requests without asking for a new document; that result does not grant a permanent exemption from future checks.
| Operator | New documents requested at first withdrawal | Withdrawal method | Confirmation of that withdrawal |
|---|---|---|---|
| 1win | Identity and address documents | Nagad | Current session password and SMS |
| Stake | No new document requested | bKash | Email link |
| 1xBet | No new document requested | bKash | SMS |
| Melbet | Source-of-funds statement | Nagad | Email and SMS |
| Parimatch | No new document requested | bKash | Authenticator-app code |
| CroreBet | Identity and address documents | bKash | SMS |
The last column identifies confirmation of a particular action by the account holder, so an accepted SMS or authenticator code should be read as that transaction's authentication step rather than as the outcome of an address-document check.
Identity and address at 1win and CroreBet
Both operators accepted my identity and address documents before approving their respective withdrawals. I used the 1win Android launcher on Xiaomi 15 Ultra. The CroreBet case ran in Chrome on Slimbook EVO 14. Each operator handled its own account and submission; neither decision was transferred to the other casino.
My 1win route began with bKash and ended with a 1,900 BDT withdrawal to Nagad. The receiving wallet belonged to the same person as the account and was permitted after checking. CroreBet's route began with Nagad and ended with a 500 BDT withdrawal to bKash, again after the requested documents had been accepted.
Those amounts identify the individual withdrawals; neither is a general KYC trigger or an amount below which documents can be avoided. The distinction also matters for the payment method: approval of my bKash-to-Nagad route at 1win is not permission to substitute another person's wallet.
A source-of-funds statement at Melbet
Melbet asked me for a statement explaining the source of funds before approving my 2,100 BDT Nagad withdrawal, which I requested in Chrome on Xiaomi 15 Ultra and confirmed through email and SMS.
The statement addressed the money's origin. An account name identifies a person. Wallet ownership connects that person to a payment account. When source of funds is requested, check which financial record the operator asks for and what it must demonstrate; another identity image may leave that question unanswered.
Withdrawals without a new document request
Stake, 1xBet and Parimatch asked me for no new document during these first withdrawals, and the wallet identity matched the account in each case. I used Safari on iPhone 15 Pro for Stake and Parimatch, and Chrome on Slimbook EVO 14 for 1xBet.
Their confirmation methods still differed, as the table shows. “No new document” describes those transactions. The wallet owner still matched the account holder. A subsequent withdrawal may involve another check, so keep the result attached to the particular transaction rather than treating it as an account-wide promise.
Approval and external receipt use different clocks
The request-to-approval interval covers the operator's checks, including KYC where it occurred, while the full interval continues until money reaches the external wallet; the longer measure therefore includes processing beyond the document decision.
| Operator | Request to approval | Request to external receipt |
|---|---|---|
| 1win | 16 min 00 sec | 27 min 03 sec |
| Stake | 4 min 29 sec | 6 min 27 sec |
| 1xBet | 10 min 11 sec | 21 min 05 sec |
| Melbet | 19 min 29 sec | 25 min 48 sec |
| Parimatch | 3 min 51 sec | 14 min 46 sec |
| CroreBet | 16 min 00 sec | 25 min 39 sec |
In my 1win case, the first interval was 16 minutes including KYC. After approval, sending took another 4 minutes 53 seconds, followed by 6 minutes 10 seconds to receipt. These stages total 27 minutes 3 seconds; adding a second, separate KYC allowance would count part of the same waiting period twice.
The table contains individual elapsed results, not advertised deadlines, averages or a promise for your account. It also shows why a fast document decision and a fast external payment are not interchangeable conclusions. For the payment stages and account-balance effects, open the withdrawal guide.
Match the document to the actual request
Identity, address, wallet ownership and source of funds are separate verification categories, so read the requested category before choosing a file: a legible document belonging to you may still answer a different question from the one being asked.
- Identity: establishes the person associated with the account. Follow the operator's stated document options for your request.
- Address: supports the residential information being checked. In 1win's anti-money-laundering terms, a utility bill is an example of address proof and must be no more than three months old. Preserve the complete document where the request requires it.
- Wallet ownership: connects the payment account with the operator-account holder. A payment receipt and the identity of its owner are different pieces of information.
- Source of funds: explains where the money came from. In the Melbet case, this required a statement rather than another confirmation code.
After registering at 1win, I confirmed my email through a link before using the cashier. The bKash wallet had already completed its own identification process, and I authorised the deposit with its PIN. 1win requested no additional document for that deposit.
At withdrawal, I confirmed the request with my current session password and an SMS code. 1win separately checked and accepted my identity and address documents before approving the withdrawal.
Fix the rejected item within the existing request
My photograph was cropped in the separate address-check case. I received a request to upload it again. Replacing it with the complete document in the same request led to approval. That branch took 9 minutes from its start to the accepted decision.
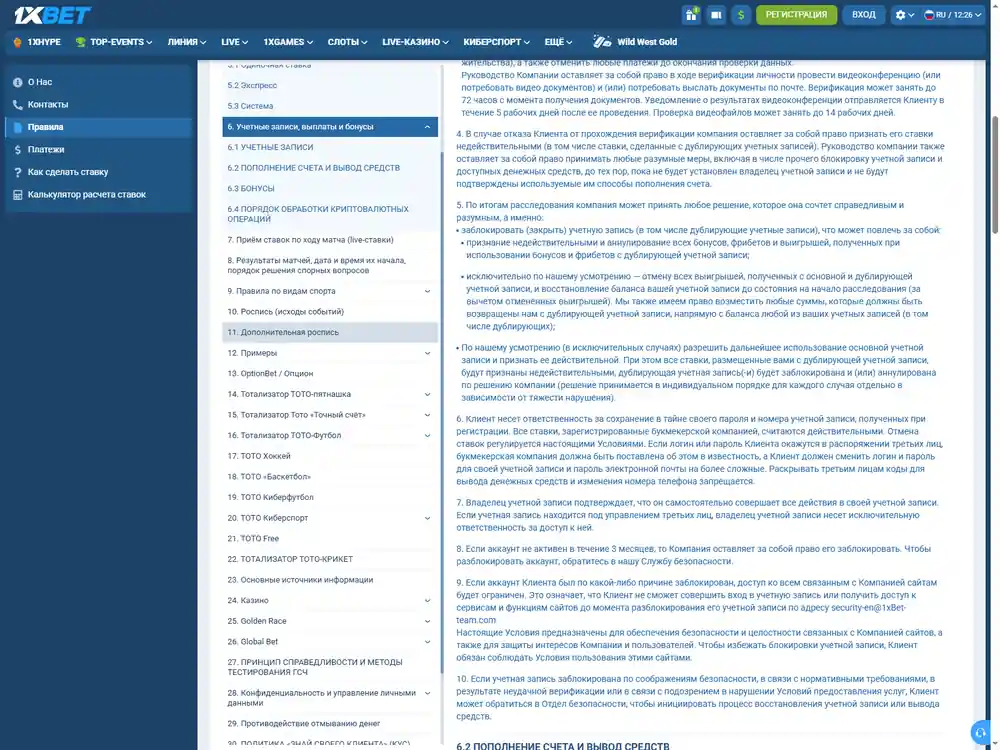
The actionable defect was the crop. Check the whole image before submitting it. The nine-minute result belongs to this correction, and another rejection may have a different cause. Follow the reason displayed for your own submission rather than repeatedly replacing an already readable file.
Tower Rush operator reviews
Six completed Bangladesh BDT tests. Scores and payment results reflect the tested accounts.
-
BDT access score7.15/10
- 96.55% configured RTP.
- 891 BDT received via bKash after a 9 BDT deduction.
-
BDT access score7.40/10
- 96.69% configured RTP.
- 1,900 BDT received via Nagad with no deduction after identity and address checks.
-
BDT access score7.15/10
- 96.19% configured RTP.
- 2,084.25 BDT received via Nagad after a 15.75 BDT withdrawal fee.
-
BDT access score7.15/10
- 97.00% configured RTP.
- 1,200 BDT received via bKash in 6 min 27 sec. The deposit had a 30.36 BDT external charge.
-
BDT access score7.40/10
- 96.65% configured RTP.
- 1,500 BDT received via bKash in full. The deposit had no external charge.
-
BDT access score7.40/10
- 96.33% configured RTP.
- 500 BDT received via bKash in full after identity and address checks.
I also completed a later small withdrawal using the existing KYC decision. Changing payment details led to a separate check of the method. Treat an approved identity decision and a changed payout destination as separate matters; do not assume that approval automatically covers every later set of payment details.
Submit a clear response and track its status
Use the document request attached to your existing operator account and check the result after submission, keeping the response connected to the outstanding question and the transaction that prompted it throughout the process.
- Open the existing account and locate the request. Read whether it concerns identity, address, wallet ownership or source of funds. If you cannot access the account, use the login and recovery guidance before trying to submit documents.
- Check the account information. Compare the name, address or payment details relevant to the request with your genuine records. Ask the operator how to correct a mismatch instead of changing a document to match an error.
- Check the requested file requirements. Use the permitted document category and inspect any stated format, size or validity requirements. Where a requirement is unclear, ask support to identify it before sending unrelated files.
- Inspect the complete image. Make sure the requested information is readable and that the document has not been cut off. The corrected address case demonstrates why an incomplete photograph can need replacement.
- Submit through the channel specified for that account request. Keep any submission acknowledgement and reference shown by the operator. Enter authentication codes only in the corresponding account or payment flow; do not include them in a document attachment.
- Read the decision and act on its reason. If replacement is requested, correct that item in the existing case. Check for an accepted decision rather than treating a completed upload as the final result.
For Tower Rush operator KYC and documents, keep the operator request as the point of reference. The registration guide covers creating an account, but a document replacement belongs to the account you already have.
Resolve a pending check with the operator
A pending document check leaves the request awaiting a decision; it does not itself mean the withdrawal or the underlying game result has been lost. In my account test, the external request remained pending while KYC was outstanding.
Contact the operator with the affected request, document category and displayed status. Include any replacement reason. Ask whether the item has been received and what action, if any, remains outstanding. Keep sensitive documents inside the designated submission route rather than posting them publicly.
Tower Rush Bangladesh publishes information and does not operate the casino account. Its editorial contact cannot approve your documents or release a payment. The support and complaints guide explains the appropriate recipient for an account issue.
Read the legal context and the explanation of real-money account boundaries before treating an accepted KYC decision or successful account access as an answer to the separate question of geographic or legal eligibility.
Questions about verification
Does Tower Rush have its own KYC account?
Verification belongs to the operator account used for real-money play. Galaxsys supplies the game, while the operator handles the document request and external withdrawal. Tower Rush Bangladesh is the informational publisher and does not collect casino-account documents for approval.
Does an SMS code replace identity documents?
No. In my 1win case, SMS confirmed the withdrawal request, while identity and address documents were separately accepted before approval. The code and the document decision performed different checks.
Can the operator ask again after a withdrawal without new documents?
Yes. Stake, 1xBet and Parimatch requested no new document in my particular first withdrawals; that did not waive future KYC. A later change to payment details can involve its own check, separate from an existing identity decision.
Should I open another account after an address-document rejection?
Correct the document within the existing request. In my repeat-upload case, replacing the cropped address photograph with the full document led to approval without creating another account. Follow the actual rejection reason rather than assuming that a new registration resolves it.
Will my document check take 9 minutes?
The nine-minute result belongs to the separate address-correction case. It is not a general deadline. The six withdrawal timings measure request approval and external receipt, with any applicable KYC included in the approval interval rather than timed as an independent service.